
 isnaini azizah
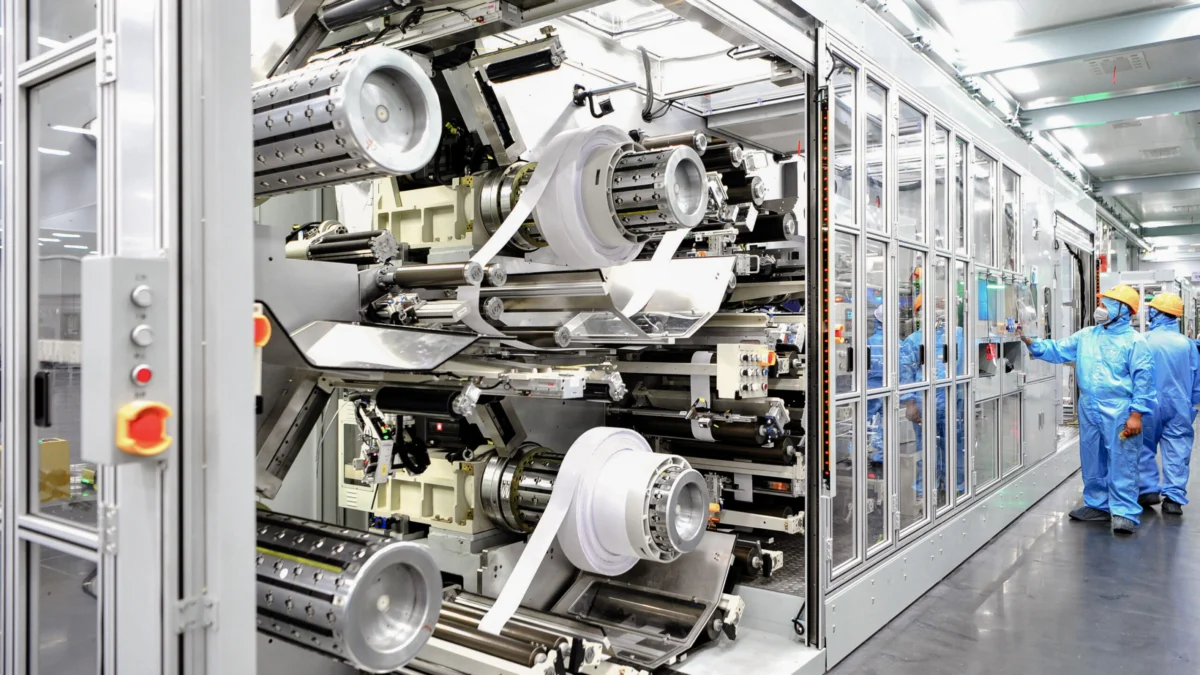
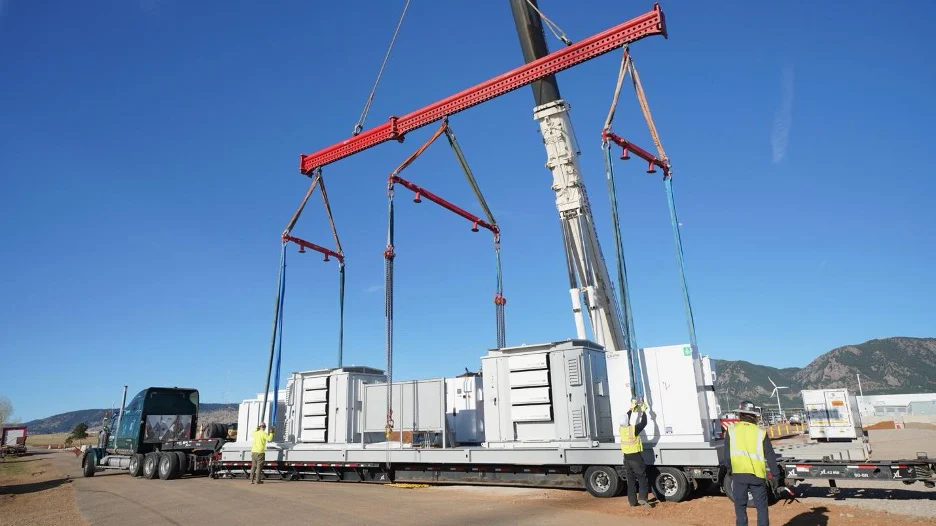
The US energy storage market is experiencing unprecedented growth, promising to bolster grid stability, enhance reliability, and significantly reduce emissions by facilitating the integration of intermittent renewable sources like wind and solar. This remarkable expansion, however, is currently heavily reliant on affordable batteries imported from China. Despite this dependency, the US has been actively pursuing strategies to diminish its reliance on Chinese battery supply chains. The most recent and assertive measure came in late August with an executive order from the Trump administration, declaring a national security emergency that effectively prohibits the use of Chinese-manufactured batteries in grid-scale energy storage systems.
This strategic pivot raises a fundamental question about national economic and technological development: to what extent should countries leverage the availability of inexpensive, globally sourced technology, versus imposing restrictions that incentivize domestic manufacturing, even if it entails higher initial costs? The US has a history of employing policy tools to decouple its battery supply chain from China. A prominent strategy has been the strategic design of tax credits, aimed at encouraging the adoption of new energy technologies. By limiting the eligibility of projects, the government seeks to level the playing field for domestically produced technologies, making them more competitive against cheaper imported alternatives.
In 2022, the tax credits established under the Inflation Reduction Act were specifically structured to dictate the provenance of battery components, restricting the sources for mineral extraction, processing, and recycling, as well as the locations for battery and component assembly. These tax credits underwent further refinement in 2025, and the Trump administration has adopted a similar approach. New legislation mandates that, commencing in 2026, at least 55% of the cost of materials utilized in new energy storage projects must originate from countries other than China and other designated restricted nations. Projects failing to meet this threshold will be disqualified from receiving tax credits.
Beyond tax incentives, tariffs have also played a significant role. In January, import taxes on batteries were substantially increased to 25%, a considerable jump from the previous 7.5%. However, the executive order issued in late August represents a more profound intervention. It declares a national emergency to protect the integrity of the United States’ bulk power system, prohibiting the installation of "any foreign-produced bulk-power system electric equipment" deemed to pose a national security risk. This order explicitly targets battery energy storage systems, alongside inverters and transformers, which are critical components of the modern grid.
The outright ban introduced by the executive order has been met with surprise and has raised concerns among domestic players within the US energy sector. Shan Tomouk, the energy storage and energy lead at Benchmark Mineral Intelligence, an esteemed energy industry analysis firm, noted that the ban was unexpected and presents challenges for American companies. This decisive action is anticipated to decelerate the deployment of grid-connected energy storage projects in the immediate future, according to analyses conducted by BloombergNEF, a leading energy consultancy. Projects may encounter delays as developers await clarification on the specific regulations and their implementation.
The Department of Energy is expected to release detailed guidance by the end of the year. Depending on this forthcoming information, some projects might be compelled to seek alternative suppliers for their battery cells, potentially turning to domestically manufactured options or imports from countries other than China. Isshu Kikuma, an energy storage analyst at BloombergNEF, suggests that these alternatives will likely be more expensive than current Chinese imports. In a worst-case scenario, he warns, some projects could be entirely canceled.
The executive order technically extends to existing energy storage facilities, though the practical enforcement of removing operational battery systems based solely on their country of origin is considered unlikely. Given that a significant portion of current grid-scale battery storage in the US utilizes Chinese-made batteries, a strict interpretation of the order would necessitate the removal of a substantial amount of installed battery capacity from the US grid.
Looking towards the longer term, the US is projected to eventually achieve self-sufficiency in battery production to meet its domestic demand. Projections indicate that the country could possess sufficient manufacturing capacity by approximately 2030. However, it’s important to note that some of these planned factories may not reach their full production capacity or ramp up as quickly as anticipated. Consequently, domestic supply may not fully align with demand until later in the 2030s.
Several significant battery manufacturers, including LG Energy Solution, Samsung SDI, Ford, and SK On, are on track to bring new factories online or expand existing operations by next year. An ironic development is the impact of a slowing electric vehicle (EV) market. This downturn is proving beneficial for grid storage efforts, as some factories originally intended for EV battery production are being repurposed to manufacture cells for grid storage applications.
However, this transition will come at a cost. Currently, batteries manufactured in the US are considerably more expensive than their Chinese counterparts. Even shifting to imports from other nations, such as South Korea, is likely to incur higher expenses. This economic disparity is a critical issue that extends beyond the US and the battery sector. China has established a dominant position globally in key clean energy technologies, including solar panels and batteries. Through years of sustained government support and extensive experience in research and manufacturing, China has emerged as a formidable energy powerhouse.
Navigating this complex landscape requires a delicate political balance. The world faces the challenge of managing the availability of cost-effective technologies that can significantly contribute to emissions reduction and lower energy costs, while simultaneously acknowledging the inherent risks of over-reliance on any single entity for critical technological supply chains.
This article is from The Spark, MIT Technology Review’s weekly climate newsletter. To receive it in your inbox every Wednesday, sign up here.